UPS, FedEx, and DHL Expand Healthcare Logistics Strategy
The short version
- UPS, FedEx, and DHL are making healthcare logistics a major growth priority.
- UPS and DHL are expanding through acquisitions and infrastructure investment.
- FedEx is growing through certifications, internal capabilities, quality agreements, and healthcare visibility tools.
- Healthcare logistics is attractive because it supports higher-value, more complex shipments.
- Carrier investment priorities can affect pricing, capacity, service design, and contract leverage.
Healthcare logistics has become one of the most important growth areas for UPS, FedEx, and DHL. This is not a side strategy. It is a direct move toward higher-value, more complex shipping.
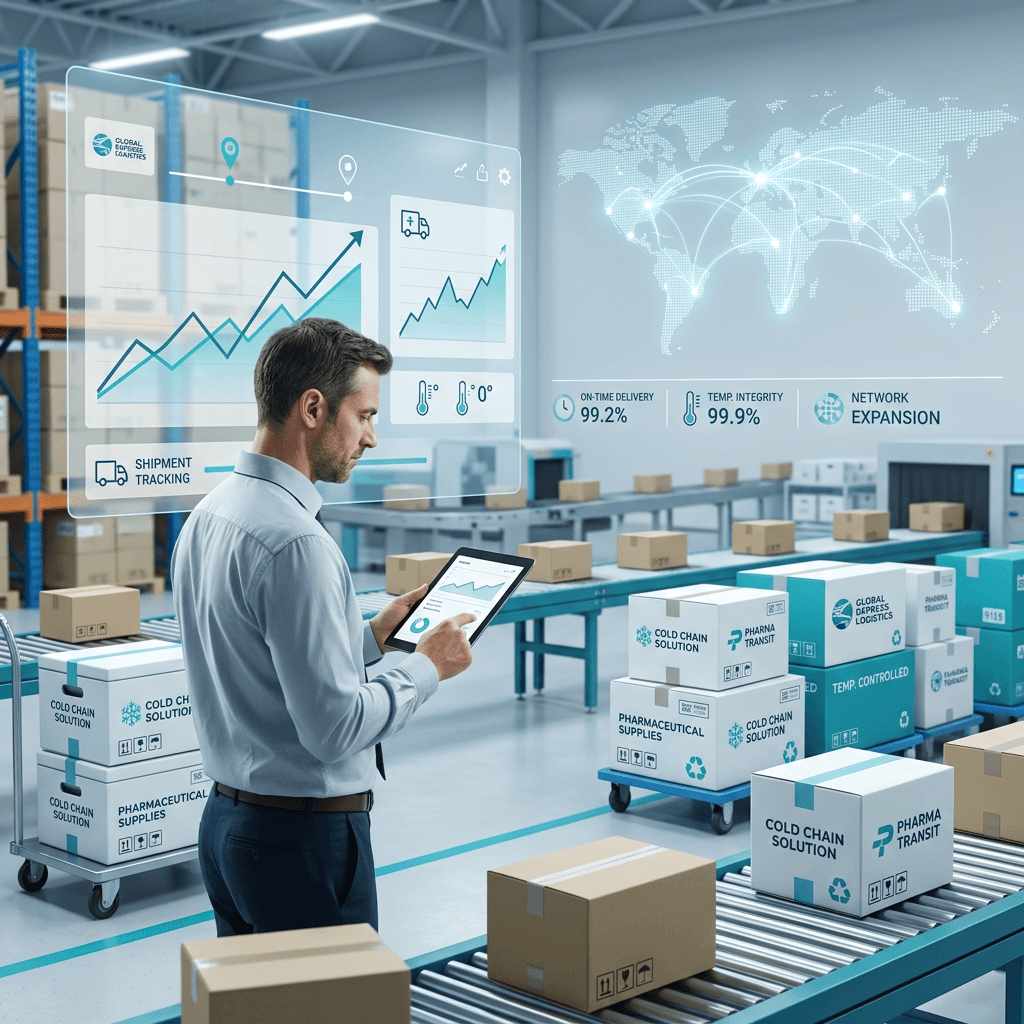
All three major global carriers are increasing their focus on healthcare logistics, including pharmaceutical, cold chain, clinical trial, and patient-facing delivery networks. The article also noted a key difference in strategy. UPS and DHL are expanding heavily through acquisitions, while FedEx appears to be building more of its healthcare network internally.
For parcel shippers, this matters because carrier investment priorities shape pricing, capacity, service design, and negotiation leverage. When carriers chase higher-margin verticals, lower-margin parcel volume can face more pricing pressure, tighter rules, and less flexibility.
Overview
UPS, FedEx, and DHL are all making larger commitments to healthcare logistics. These services often require temperature control, regulatory compliance, specialized handling, global visibility, and reliable final-mile execution.
- UPS has expanded through several healthcare acquisitions. Its $1.6 billion acquisition of Andlauer Healthcare Group expanded its cold chain and pharmaceutical logistics capabilities across North America. UPS also completed the acquisition of Frigo-Trans and Biotech & Pharma Logistics in January 2025, strengthening its European healthcare cold chain network.
- DHL has also moved aggressively. DHL announced a €2 billion investment through 2030 to expand life sciences and healthcare logistics capabilities. DHL also completed its acquisition of SDS Rx, which adds specialized final-mile healthcare transportation across more than 200 U.S. locations. DHL also acquired CRYOPDP to strengthen its biopharma, clinical trial, and advanced therapy logistics capabilities.
- FedEx has taken a different path. FedEx became the first global integrator to achieve IATA CEIV Pharma certification for ground handling across its air hubs and ramps. FedEx also reported nearly $400 million in new annualized healthcare revenue in 2025 and more than $500 million in healthcare agreements in fiscal 2024.
What Changed
The major carriers are no longer treating healthcare as a niche service line. They are building healthcare logistics into their long-term growth plans.
Key changes include:
- UPS is buying specialized healthcare networks to expand cold chain, pharma, and clinical logistics.
- DHL is using acquisitions and capital investment to grow life sciences, healthcare, same-day, and final-mile healthcare delivery.
- FedEx is investing in certifications, visibility tools, quality agreements, and internal healthcare capabilities.
Healthcare logistics is becoming more patient-facing, more temperature-sensitive, and more compliance-driven. The largest carriers are using healthcare to grow higher-yield revenue, not just shipment volume.
Why This Matters for Parcel Shippers
This shift shows where the carriers want to grow.
Healthcare freight often carries higher value, stricter service requirements, and better margins than standard ecommerce parcel volume. That makes it attractive to carriers. It also means general parcel shippers need to understand how carrier priorities may change.
When carriers focus more on specialized verticals, they may become more selective with capacity and pricing. They may prioritize accounts that fit their preferred revenue profile. They may also become less willing to discount services that do not align with their margin goals.
This does not mean ecommerce, retail, manufacturing, or consumer goods shippers will lose access to capacity. It does mean they should expect more disciplined pricing, more surcharge enforcement, and less tolerance for inefficient freight.
Cost and Contract Implications
Healthcare investment affects more than healthcare shippers. It can influence the broader parcel market.
1. Higher-margin freight can change carrier discount behavior
UPS, FedEx, and DHL are investing in services that support premium pricing. These include cold chain, healthcare final mile, clinical trials, specialty pharmacy, and temperature-sensitive transportation.
As carriers build more revenue from these areas, they may reduce their dependence on lower-margin parcel volume. That can weaken a shipper’s leverage if their freight profile is costly to serve.
2. Service commitments may become more segmented
Healthcare shipments often require stricter handling, visibility, chain of custody, and delivery reliability. Carriers may continue building premium service models around these requirements.
That can create a wider gap between standard parcel service and premium vertical-specific service. Shippers should watch how this affects guarantees, exception handling, delivery visibility, and claims support.
3. Accessorials may become more important
Specialized networks require more infrastructure. That cost often shows up through surcharges, compliance fees, handling fees, pickup charges, delivery area charges, and contract-specific pricing rules.
Even non-healthcare shippers can feel the impact if carriers tighten operational requirements or expand fee structures across broader customer groups.
4. Contract language needs closer review
Shippers should review more than base discounts. They should examine:
- Minimum charges
- Fuel surcharge tables
- Delivery area surcharges
- Residential fees
- Additional handling rules
- Large package charges
- Dimensional weight terms
- Service guarantees
- Compliance requirements
- Early termination language
- Rate cap protections
Carrier agreements need to reflect how carriers actually price and manage networks today.
5. Multi-carrier strategy becomes more valuable
A shipper that relies too heavily on one carrier has less leverage when that carrier shifts its commercial priorities. Healthcare logistics growth is another reminder that carrier networks are not static.
Shippers should compare UPS, FedEx, DHL, USPS, regional carriers, and final-mile providers by lane, package profile, service need, and total landed cost.
What Shippers Should Do Next
Shippers should take the following steps now:
- Audit your current parcel agreement for surcharge exposure.
- Compare your discounts against current market benchmarks.
- Model your total landed cost by service, zone, weight, dimensions, and accessorial type.
- Identify shipments that are expensive for carriers to handle.
- Separate profitable volume from high-cost volume before negotiations.
- Review claims, service failures, and billing adjustments.
- Build a carrier strategy that does not depend on one provider.
- Track carrier investment priorities because they often signal future pricing behavior.
How ebb Logistics Can Help
Ebb Logistics helps parcel shippers understand how carrier strategy affects their shipping costs. We benchmark your current agreement against the market, identify cost leakage across base rates, surcharges, accessorials, and contract terms and we model your shipping data to show where your parcel spend is exposed. In this process, we build you stronger negotiation strategy. That includes carrier comparisons, surcharge controls, service-level analysis, and multi-carrier planning.
The goal is simple. You should know what you are paying, why you are paying it, and where better options exist.
Call to Action
Healthcare logistics is one example of how fast carrier strategy is changing. If your parcel agreement has not been benchmarked against current market conditions, your company may be overpaying. ebb Logistics can review your parcel data, identify cost leakage, and show where your carrier agreement can be improved. We have found that 99% of the clients you ask of for a risk free assessment learn that we can help save them between 15-25%.
Contact ebb Logistics today for a no-obligation parcel agreement review.